
Small Business
Why Google Is Spending $1 Billion On Its Offices—And Other Small Business Tech News This Week – Forbes
Neque porro quisquam est, qui dolorem ipsum quia dolor sit amet, consectetur, adipisci velit, sed quia non numquam eius.


Woman Restaurant Owner With Waiting Staff
The Great Resignation has made attracting and retaining employees a top priority. After health insurance, providing retirement benefits is the second most frequently offered benefit to attract talent. State and city regulation is prompting more interest in 401(k) plans, too! More than one-third of small businesses that do not currently offer 401(k) plans expect to within 12 months.
A 401(k) retirement plan is also a way to take care of employees’ financial wellness and provide a tax benefit to companies and their employees. But legacy 401(k) providers avoid marketing to the smallest businesses because the market isn’t very profitable. Yet, the vast majority of companies have fewer than 20 employees.
Penelope is a 401(k) platform that gives small businesses an affordable and east-to-use way to provide retirement benefits. It is helping small businesses navigate the challenges of the Great Resignation. At the same time, its CEO and founder, Jean Smart, manages her own challenges.
Jean Smart, CEO and founder at Penelope—a 401(k) retirement benefits platform for small businesses
Smart is a founding member of Chief, a private network for influential women leaders. She became part of a peer-advisory group with female founders and corporate executives who have similar interests and challenges and help each other problem-solve. One founder in Smart’s peer group has already achieved unicorn status—a billion-dollar-plus valuation.
Smart had worked in companies like Citi, Charles Schwab, and TD Ameritrade, and at the time, UBS. She worked on institutional employee benefits, such as 401(k) plans, employee stock options, and financial wellness. Inspired by the female founders in her Chief group, Smart started developing a business concept of her own.
Smart, the daughter of Korean immigrants who own a grocery store and restaurant, saw how her parents sacrificed to provide for their children and employees while neglecting to save for their retirement. Not saving has left them vulnerable in their later years. «With one in four Americans having no retirement savings, my parents are an all too familiar story in the U.S.—equal parts inspiration and cautionary tale,» said Smart.
«I’m a Gen-Xer and I’ve heard my entire life that we’re going to run out of Social Security,» said Smart. For many Americans, Social Security provides an essential source of income in retirement. But its money is running out. Projections say that starting in 2034; the Social Security Administration will reduce retirement benefits.
Smart’s personal and professional background made her think she was the right person to tackle this problem.
«I wanted to do something around fintech, education, and inclusive capital,» said Smart. She wanted to dispel the notion that there was a quick way of getting rich. Investing regularly in a 401(k) was the way to build a nest egg for retirement. «The reality is it takes generations to build wealth,» she sighed. «It doesn’t happen overnight, and it takes people working 20, 30, 40 years before they have money to pass on [to loved ones].» She wanted to create a way to set it and forget it.
Businesses with fewer than 20 employees—the vast majority—of small businesses need help, thought Smart. Many of these businesses are owned by women, minorities, and immigrants. Fintech streamlined processes, allowed her to simplify paperwork, and helped her cut costs by using a self-serve business model, making it affordable for small businesses to provide retirement benefits for their employees.
«It’s hard making things simple,» said Smart. «There are 50 to 60 thousand funds to choose from. We offer 10. The trade-off is there isn’t customization.» Through a low-cost subscription model, Penelope’s technology platform automates employee investing, streamlines cost and paperwork, provides practical savings tools for employees, and offers the choice of Pooled Employer Plans (PEP), traditional 401(k)s and Solo 401(k)s.
Penelope is an intuitive, cloud-based 401(k) platform, which launched in January. There are no 30-to-40 page documents with complicated jargon, and the content is brief, to the point, and uses plain English. People have different learning styles, so content is provided as text and FinTok videos.
Timing can be everything. More and more states and cities are mandating that businesses provide retirement benefits. California, Oregon, Illinois, Maryland, Colorado, Connecticut, New York City, New Jersey, Virginia, Seattle, and Maine do so. Rules and regulations vary, depending on where your business operates.
«During the Great Resignation, we’re all fighting to get the best people,» said Smart. She relies on referrals, and, fortunately, she is well connected.
Her employees could undoubtedly make more money working in larger companies as a startup. But Smart emphasizes the company’s purpose. «The fact that we are mission-based is very attractive,» she said. «It’s really striking a chord, not just with professionals in their 20s and 30s, but also their 40s, 50s and even their 80s. I’ve got five generations working with me,» Smart proudly said.
She recruited Ted Benna, widely known as the «father of the 401(k),» as an advisor to Penelope. «I’ve helped a lot of small businesses in my lifetime, as well as running my own business, and for many of them, the idea of offering a 401(k) was out of reach, expensive and confusing, filled with jargon and too time-consuming,» said Benna. «Penelope provides plans that are easier to understand and economically make sense for small businesses and startups.»
Shifting from a well-resourced mindset to a resource-constrained startup has been a steep learning curve for Smart. «You’re working with a blank slate,» she said. «You make many mistakes. You have to be open.” You have to be an agile leader, and there are ways to improve your adaptability. Once you have, «it’s thrilling.»
Penelope has successfully raised $2.1 million in pre-seed fundraising led by Slauson & Co. Additional investors include Amplify LA, Black Jays and executives from Wells Fargo, Citigroup and US Bank. “Saving for retirement is an essential tool for building wealth and financial equality,” said Austin Clements, Managing Partner at Slauson & Co. “Penelope fundamentally changes the way small business owners and employees invest in themselves, their families and their communities.”
How are you taking advantage of your experience and market trends to launch or re-calibrate your business?





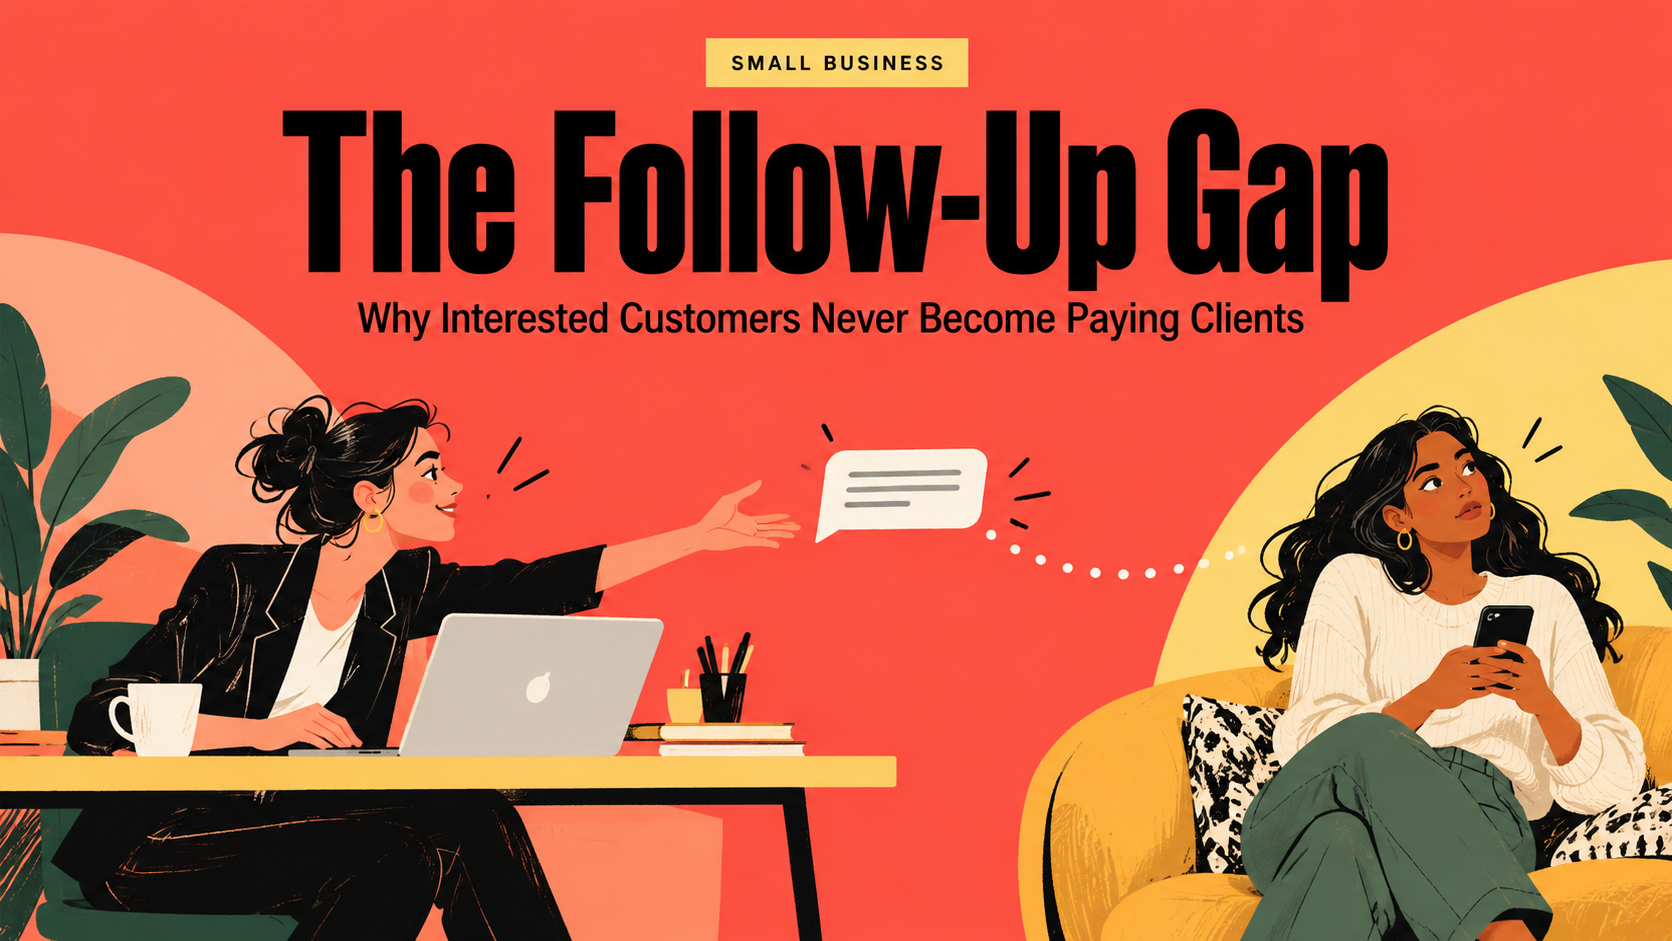
A potential customer asks for pricing. The owner sends a proposal, receives no reply, and moves on. Two weeks later, neither person has taken another step. The business cannot tell whether the prospect lost interest, became busy, or still has an unanswered question.
Follow-up helps resolve that uncertainty. It gives an interested person a clear path toward a decision while helping the business understand which opportunities are still active.
Make the next step clear
A conversation can feel productive without producing a commitment. Before it ends, agree on what happens next. Will the prospect review a proposal, book a call, or confirm a start date? Ask when a follow-up would be helpful. “May I check back on Thursday after you have reviewed the details?” is easier to act on than “Let me know.”
Keep a record of the actual conversation
Record what the person asked for, the problem they want to solve, their timing, and any concerns they raised. A spreadsheet or customer relationship management system can help. The important part is keeping a reliable record with a next action and a responsible team member. Avoid collecting personal details that are unnecessary for serving the prospect.
Give each message a purpose
A useful follow-up adds context or removes an obstacle. If someone asked about scheduling, send the available dates. If they questioned fit, explain who the service is designed to help and where its limits are. A relevant example may help them evaluate the offer, provided you have permission to share it and represent the result accurately.
For example: “Hello Jordan, you mentioned wanting to start next month. I have included the two scheduling options we discussed. Would either work for your team, or has your timeline changed?” The message is specific and leaves room for an honest answer.
Use a reasonable follow-up rhythm
Build the timing around the buyer’s decision process and any agreement you made. An urgent service request and a large annual purchase may require different approaches. Avoid treating every unanswered message as permission to contact someone daily. Honor requests to stop, and make it easy for people to decline.
Know when to close the conversation
An opportunity should not stay open forever simply because no one said no. Send a brief closing message when appropriate: “I will close this inquiry for now. If the timing changes, you are welcome to reach out.” That creates a clear stopping point without pressure.
Review where conversations stall. If prospects repeatedly ask the same question, improve the proposal or sales conversation. If replies go unanswered internally, fix ownership and response handling. Better follow-up begins with making the buying process easier to understand.
Small Business
Small Business Confidence Is Rising Again—But Growth Comes With a New Set of Challenges

After months of economic uncertainty, there are signs that America’s small-business economy is regaining some momentum. Entrepreneurs are starting companies at a faster pace, existing business owners are becoming more optimistic, and more employers are preparing to hire.
But this is not a return to easy growth.
The small-business environment of 2026 is increasingly defined by a different challenge: owners may see opportunities to expand, but finding the right employees, managing financing costs, protecting margins and making smart investments are becoming critical to turning optimism into sustainable growth.
Confidence Is Returning to Main Street
The latest numbers offer an encouraging picture.
The National Federation of Independent Business reported that its Small Business Optimism Index increased 2.4 points to 99.8 in July 2026, putting it above its long-term average of 98 and at its highest level since August 2025. Eight of the index’s ten components improved during the month.
Perhaps more important is what business owners intend to do next.
A seasonally adjusted net 20% of small-business owners said they planned to create jobs during the next three months, the strongest hiring intention recorded since October 2022. Meanwhile, 25% planned capital expenditures during the next six months, the highest level since December 2024.
That combination suggests small-business owners are not simply feeling more confident. Many are beginning to think about expansion again.
And new entrepreneurs continue to enter the market.
The U.S. Census Bureau reported 578,926 business applications in July 2026, seasonally adjusted, an 8.1% increase from June. The agency projected nearly 30,000 new employer businesses would emerge within four quarters from July’s applications.
Entrepreneurial activity, in other words, remains alive and well.
The Biggest Problem Is Shifting
For much of the past several years, inflation dominated business conversations. Rising materials, transportation, energy and operating expenses forced many small companies to increase prices or accept thinner margins.
Those pressures have not disappeared, but the latest data suggest the concern is changing.
In July, 14% of surveyed small-business owners identified inflation as their most important business problem, down seven percentage points from June. At the same time, 27% identified labor quality or availability as their biggest problem, making workforce issues the leading concern.
Thirty-six percent reported job openings they could not fill, the highest percentage since June 2025. Among businesses hiring or attempting to hire, a large majority reported receiving few or no qualified applicants.
That creates an unusual situation.
Businesses increasingly want to hire at the same time that many cannot find the people they need.
For small companies, this problem can be particularly serious. Large corporations may have dedicated recruiters, larger salary budgets and stronger employer brands. A business with 10 or 20 employees often does not have those advantages.
The result is that the next stage of small-business competition may be fought as much over talent as customers.
Small Businesses Need to Rethink Hiring
Throwing another job listing online may no longer be enough.
Owners looking to expand should increasingly think about the employee experience in much the same way they think about the customer experience.
Competitive pay matters, but so do scheduling flexibility, career development, workplace culture, training and clear opportunities for advancement.
Small businesses can also compete in ways that larger companies sometimes cannot.
They can give employees greater responsibility earlier. They can make decisions faster. Employees may have more direct access to leadership and a clearer understanding of how their work affects the company.
Those advantages need to become part of the recruiting message.
Businesses should also reconsider whether every position requires an experienced candidate. When qualified talent is scarce, hiring capable people and developing them internally can sometimes be more effective than waiting months for a perfect résumé.
Growth Still Needs Financial Discipline
Improving confidence should not be confused with inexpensive money.
NFIB’s July survey found that the average interest rate owners reported paying on short-maturity loans was 7.9%. Meanwhile, Federal Reserve lending data showed that credit standards remained toward the tighter end of their historical range across many lending categories, even as conditions for commercial and industrial lending were relatively more accommodating.
That means expansion decisions need to be deliberate.
Buying equipment, opening another location or adding employees may create growth, but only when the expected return justifies the cost.
Owners should know three numbers before committing to major expansion: the additional monthly cost, the realistic revenue the investment can generate, and how long the business can comfortably carry the expense if sales develop more slowly than expected.
In an uncertain economy, cash reserves and flexibility can be just as valuable as rapid growth.
Protecting Margins Matters More Than Chasing Revenue
Revenue growth looks impressive, but profitability keeps businesses alive.
Small-business owners should therefore pay close attention to which products, customers and services actually produce their strongest margins.
Some businesses may discover that a relatively small group of customers generates most of their profit. Others may find that an apparently popular product consumes too much labor, inventory or delivery expense to remain worthwhile.
The strongest companies will use this period of improving confidence to become more selective—not simply bigger.
That could mean eliminating low-margin offerings, renegotiating supplier contracts, introducing minimum order requirements, adjusting pricing or focusing sales efforts on the customers most likely to become profitable long-term relationships.
The Opportunity Is Real, but So Is the Uncertainty
The current numbers are encouraging, but business owners are hardly carefree.
NFIB’s Uncertainty Index increased to 91 in July, remaining well above its historical average. Sales expectations also softened slightly even as overall confidence improved.
That combination captures the current small-business environment remarkably well.
Owners are optimistic enough to invest.
They are cautious enough to know conditions can change.
That may actually be a healthy combination.
The businesses positioned to perform best in the next phase are unlikely to be those that expand at any cost. They will be companies that grow selectively, recruit creatively, control expenses, preserve cash and remain close enough to their customers to recognize changes in demand early.
A New Phase for Small Business
Small-business optimism returning above its long-term average is meaningful. Rising business applications are meaningful too.
They show that entrepreneurs continue to believe there are opportunities worth pursuing despite a complicated economic environment.
But 2026 is also demonstrating that optimism alone does not build a successful company.
Execution does.
For entrepreneurs, the opportunity now is to turn improving confidence into stronger businesses without repeating the mistakes that often accompany rapid expansion.
The next winners in small business may not be the companies that grow the fastest. They may be the ones that learn how to grow without losing control.
Featured
The 2026 Small Business Opportunity: How Entrepreneurs Can Turn Economic Change and AI Into Growth
Running a small business in 2026 requires entrepreneurs to pay attention to two economies at the same time.
There is the traditional economy of prices, employees, interest rates and consumer spending.
Then there is the rapidly developing digital economy being shaped by artificial intelligence.
For entrepreneurs willing to understand both, the current environment may create opportunities to operate smarter, control costs and compete with companies much larger than their own.
There Are Signs of Relief—but Business Owners Should Remain Cautious
New economic data released August 13 showed that U.S. producer prices were unchanged in July after declining slightly in June. Goods prices fell 0.7%, while the cost of services increased 0.2%. Producer prices were still 4.7% higher than a year earlier, meaning inflation has not disappeared.
For business owners, that creates a mixed picture.
Certain expenses may begin to stabilize, but entrepreneurs should not assume that everything is going back to pre-inflation pricing.
This is the time to understand the numbers inside the business.
Owners should know their customer acquisition cost, profit margins, operating expenses and the amount of revenue generated by each major product or service.
When the economy is uncertain, cash-flow visibility becomes even more important.
Productivity Is Becoming the New Growth Strategy
One encouraging development has been productivity.
U.S. nonfarm productivity increased at a 1.4% annualized rate during the second quarter of 2026 and was 2.2% higher than a year earlier. Economists and policymakers are watching whether continued AI investment will help increase productivity further.
For the small-business owner, productivity means something very practical:
How can you produce more value without simply working more hours?
The traditional entrepreneurial response to growth is often to hire more people, work longer hours or spend more money.
Technology offers another option.
Businesses can increasingly automate repetitive work while allowing owners and employees to spend more time on activities directly connected to revenue and customer relationships.
Small Businesses Are Using AI—but Many Have Barely Scratched the Surface
There is a noticeable difference between using AI and actually building AI into a business.
Goldman Sachs reported in March that 76% of small businesses participating in its survey were using AI, with 93% of users reporting a positive impact. However, only 14% said AI had been fully integrated into their core operations.
Broader Census Bureau data paints an even more cautious picture. From December 2025 through May 2026, overall business AI usage measured by its Business Trends and Outlook Survey remained around 17% to 20%, with adoption generally higher among larger companies. Less than 20% of businesses with four or fewer employees reported using AI.
The surveys measure AI use differently, but together they highlight an important opportunity.
Most entrepreneurs are still figuring this out.
That means the competitive advantage has not disappeared.
Start With the Work You Do Every Week
Small businesses do not need complicated AI strategies to begin.
Start by looking at tasks repeated every week.
For example:
- Following up with potential customers
- Answering frequently asked questions
- Creating social media content
- Writing email campaigns
- Preparing proposals
- Organizing meeting notes
- Researching potential clients
- Creating basic reports
- Scheduling appointments
- Reviewing customer feedback
Then ask:
Which of these activities can technology make faster without lowering the quality of the customer experience?
Saving 30 minutes once is useful.
Saving 30 minutes on a task performed every day can change the economics of a business.
Do Not Use AI Simply to Produce More Content
One of the easiest traps for entrepreneurs is using AI only to create more posts, emails and articles.
That is useful, but it is only the beginning.
A more important question is how technology can help the company produce more revenue.
Could AI help identify better prospects?
Could it shorten response times?
Could it improve customer follow-up?
Could it analyze why customers are leaving?
Could it help employees serve twice as many customers?
Those questions move AI from a content tool to a business-growth tool.
Protect the Human Advantage
Small companies possess something many large corporations spend millions trying to recreate:
personal connection.
Customers can often speak directly with the owner.
Employees know customers by name.
Decisions can be made quickly.
The business can adapt without going through several management levels.
Entrepreneurs should be careful not to automate away that advantage.
Use technology to eliminate unnecessary work so that people have more time for relationships, not less.
Think in 90-Day Business Cycles
This environment rewards entrepreneurs who move quickly.
Instead of creating a giant three-year technology plan, business owners can select one measurable goal for the next 90 days.
Increase leads.
Improve customer retention.
Reduce administrative time.
Increase sales conversions.
Improve profit margins.
Then identify two or three tools or processes that could help reach that specific goal.
Test them.
Measure the results.
Keep what works.
Remove what does not.
Then begin another 90-day cycle.
Small Businesses Can Still Move Faster Than Big Businesses
Large corporations may have more employees, larger budgets and massive technology departments.
Small businesses have another advantage.
They can move.
An entrepreneur can identify a problem Monday, test a solution Wednesday and change the entire process by Friday.
That ability to move quickly becomes extremely valuable when technology and economic conditions are changing this fast.
The small businesses that grow over the next several years will not necessarily be the ones spending the most money.
They will be the ones paying attention, protecting their cash, embracing useful technology and making better decisions faster than their competitors.
In 2026, being small does not have to be a disadvantage.
When combined with technology, focus and speed, it may become one of a company’s greatest advantages.
-

 Leadership2 years ago
20 Entrepreneurs to Watch Closeout 2024
-
 Real Estate2 years ago
Startups Are Looking To Fractionalize Real Estate Assets, But Should They? – Forbes
-
 Innovation3 years ago
Leo Horacio: A Successful Entrepreneur in the Ecommerce and Online Sales Industry
-

 Innovation2 years ago
Innovators in Social-Emotional Learning: Dr. Myava Clark and Chris Clark Jr.
-

 Music2 years ago
Artist Deydee Signs $350,000 Contract with Rueda Empire LLC
-
 Latest2 years ago
Florida Gov DeSantis signs 15-week abortion ban | Latest News
-
 Money2 years ago
Trailblazer in Business: Alicia Fitts on Building Wealth and Community Through Faith
-
 Latest2 years ago
Charles zhang recognized by forbes as #1 on michigan’s 2022 best in state wealth advisor list